Key figures
- 136.0 pointsFAO Food Price Index for September 2026, 5.8% above a year earlier, with the cereal index up 17.2%.FAO
- $858/tonaverage US retail urea price in the week of 13 April 2026, 48.7% higher than a year earlier.farmdoc daily, citing DTN
- 45 millionadditional people the World Food Programme (WFP) said could be pushed into acute hunger if the conflict continued through June.UN News
- 35%year-on-year rise in average wheat prices by mid-September 2026; maize was up 24%.World Bank
- More than 90%share of Ethiopia's nitrogen fertiliser that comes from the Gulf.AP
Why nitrogen matters for crop yields
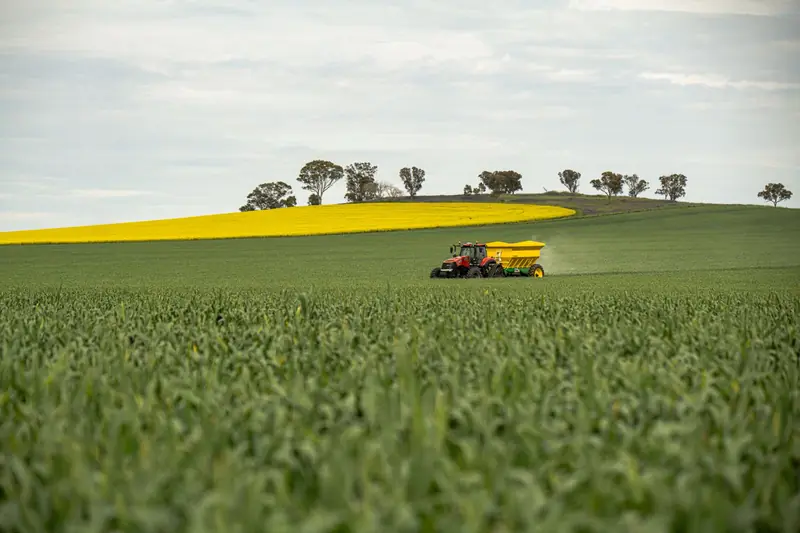
Nitrogen is the nutrient that most directly drives yields of maize, wheat and rice, and urea is the most widely traded nitrogen fertiliser [13]. Timing matters as much as quantity. Fertiliser is usually applied at or just before planting, and crops that miss nitrogen in their early growth stages can lose yield even if supplies recover later. One economist cited Zambian research showing that even short delays can cut maize yields by about 4% in a season [13].
Application rates in intensive systems are high: Illinois recommendations for 2026 corn were about 180–200 lb of nitrogen per acre [11]. This is why a fertiliser shortage matters for food prices. When farmers buy less nitrogen or apply it late, the effect appears months later in smaller harvests.
The 2026 Iran war hit this input directly. The Middle East supplies about a third of global urea exports [7], and the Gulf up to 30% of ammonia [2]; disruption to shipping through the Strait of Hormuz kept much of that supply from the market for months. In early October, IFPRI reported that fertiliser shipments through the strait were still "close to zero" in mid-September [16]. For the gas and LNG side of the story, see our analysis of LNG, gas prices and urea.
Fertiliser prices and the affordability squeeze
Prices moved first. The World Bank reported urea above $850/t in April, up 80% since February and the highest since April 2022 [3]. In the United States, the average retail urea price reached $858/ton in the week of 13 April, 48.7% higher than a year earlier [11]. In Brazil, local fertiliser prices rose by more than 35% in the first two weeks of the conflict [7].
The squeeze comes from the gap between input costs and crop prices. Analysts measure it with affordability ratios: the price of a fertiliser divided by the price of the crop it is applied to. The World Bank said fertiliser affordability had fallen to its weakest level since mid-2022 [3]. Its April Commodity Markets Outlook projected a 31% rise in its fertiliser price index in 2026, against a 2% rise in food prices [4]. Purdue University economists noted a key difference from 2022: then, rising input costs coincided with a strong rise in crop prices, whereas in 2026 corn and soybean gains have been much smaller [12].
farmdoc daily estimated that the spring price rise added roughly $30–55 per acre to US corn nitrogen costs, equivalent to about 7–13 bushels of corn per acre. In a Farm Bureau survey it cites, about 70% of respondents nationally said they could not afford all the fertiliser they needed [11].
Nitrogen prices have since eased. IFPRI found that urea was almost 80% above its 1 January level in late April but back to January levels by the end of August, with nitrogen prices down 25–45% from late May [6]. The World Bank's fertiliser index fell from 156.1 in June to 146.4 in August, and urea dropped to $400/t in July [5]. Affordability has improved unevenly. In July the Agricultural Market Information System (AMIS) reported that the US urea-to-maize ratio was back to its level at the start of 2026, while affordability "remains historically weak for European farmers" [10].
Planting decisions and application rates
Agencies warned early that a cost shock could turn into a yield shock. In April, FAO chief economist Máximo Torero said that if the conflict lasted beyond 40 days, farmers might use fewer inputs, plant less or switch to less fertiliser-intensive crops, and that these choices would hit future yields [2]. Argus's head of agricultural pricing said wheat and corn were more exposed than rapeseed, sunflower and soybeans [2].
Some of this shift is visible in the United States. The US Department of Agriculture's (USDA) Prospective Plantings report in March put corn intentions at 95.3 million acres, down 3% on 2025, and soybeans up 4%. All-wheat area of 43.8 million acres was the lowest since records began in 1919 [14]. Industry analysts said many 2026 decisions had already been made because fertiliser was in the ground, and that the larger effect could come with autumn applications for 2027 [14].
Buyers are cautious elsewhere too. AMIS reported that EU buyers were postponing purchases for next season and US buyers were reluctant to extend nitrogen coverage [10]. An OECD analysis cited by AMIS found that lower fertiliser application in response to higher costs could leave South Africa's cereal output around 5% below baseline in 2026 and 2027, and India's about 2% lower, with smaller declines in most OECD countries [10].
How fertiliser shortages feed into food prices
The link to food prices runs through harvests, so it is slow. IFPRI researchers note that higher farm and energy costs can take three to six months to reach store prices in high-income countries, and that the effect can last 12 to 18 months [7].
FAO's Food Price Index averaged 136.0 points in September, 5.8% above a year earlier but 15.1% below its March 2022 peak. The cereal index rose 5.1% in the month and was 17.2% higher year on year. FAO said uncertainty over shipping through Hormuz kept concerns about fuel, fertiliser and freight costs elevated [1].
Grain markets have tightened since mid-year. The World Bank reported that maize prices rose 26% and wheat 22% between June and mid-September; year on year, wheat was up 35%, maize 24% and rice 13%. It cites a forecast that global wheat production in 2026/27 will be 3.8% below the previous season, and El Niño is expected to strengthen into early 2027 [5].
Households feel this most where food takes a large share of income. In low-income countries households spend around half of their income on food, so a 10% rise in food prices cuts disposable income by about 5% [7]. In March, WFP said that if the conflict continued through June, an additional 45 million people could be pushed into acute hunger by price rises [9].
Which regions are most vulnerable?
Exposure depends on import dependence, reliance on the Gulf and farmers' ability to absorb higher costs.
- Sub-Saharan Africa. About a third of East Africa's fertiliser supplies come from the Gulf [7], and Ethiopia sources more than 90% of its nitrogen fertiliser from the Gulf via Djibouti [13]. WFP noted that the disruption came as the region entered a planting season [9]. The World Bank projects that about 62 million people in Eastern and Southern Africa will need urgent food assistance by March 2027 [5].
- South Asia. Lower LNG supply led India to cut urea and ammonia output [3]. Its nitrogen imports rose 52% in the first half of 2026, and its fertiliser subsidy bill may exceed 3 trillion rupees ($31 billion), against a budgeted 1.71 trillion [6]. A new OECD brief points to larger effects on cereal production and calorie availability per person in Southern Asia and sub-Saharan Africa [15].
- Latin America. Brazil imported 88% of its fertiliser in 2025, including 95% of its nitrogen [12], and about 40% of its imports come via Hormuz [7]. Its nitrogen imports fell 19% in the first half of 2026 [6], and soybean growers faced the purchasing window for the 2026/27 crop during the price spike [12].
Lessons from 2022
Urea prices peaked in April 2022 at more than three times their 2019 average [15]. Fertiliser prices rose 56% that year, and the ratio of fertiliser prices to wheat, maize and soybean prices rose by about 50%; for rice it more than doubled [8]. Global fertiliser demand fell from 200 million tonnes to 192 million tonnes in 2022/23, and Africa's demand for nitrogen, phosphate and potash fell about 14% in 2021/22 [8]. IFPRI concluded that commercial farmers largely absorbed the shock, while smallholders, especially in Africa, were likely hit harder [8].
Three differences stand out in 2026. First, crop prices had not risen before the shock, so margins were thinner [12,13]. Second, the World Bank said the 2026 price rise was smaller than in 2021–22, partly because Northern Hemisphere growers had already secured supplies and gas prices rose less sharply [3]. Third, governments have again cushioned costs: an EU framework allows member states to cover up to 70% of farmers' additional fuel and fertiliser costs [6]. The OECD notes that stocks and purchases made before a price rise may protect one planting season, and that soil testing and better-targeted application can improve efficiency [15].
What to watch
- Autumn applications for 2027 crops in the Northern Hemisphere, where analysts expect the larger acreage effect [14].
- India's rabi season, for which IFPRI flagged uncertain fertiliser availability [7].
- Affordability ratios in AMIS and World Bank updates, and FAO's next Food Price Index on 6 November [1].
- Gulf export recovery. IFPRI estimated that fertiliser markets would not normalise before the end of 2026 even if the conflict ended in mid-June, and that a prolonged conflict could extend the crisis into 2028 [7].
Alupetra follows urea and fertiliser markets from its offices in Istanbul, London and Dubai.
Sources
- FAO — FAO Food Price Index (release of 2 October 2026). fao.org (opens in a new tab)
- AGBI (Reuters) — Iran war will reshape global crop choices, UN warns (9 April 2026). agbi.com (opens in a new tab)
- World Bank Blogs — Fertilizer prices surge as Strait of Hormuz disruptions tighten supplies (14 May 2026). blogs.worldbank.org (opens in a new tab)
- World Bank Blogs — The Commodity Markets Outlook in eight charts (30 April 2026). blogs.worldbank.org (opens in a new tab)
- World Bank — Food and Nutrition Security Update, September 2026 (28 September 2026). worldbank.org (opens in a new tab)
- IFPRI — How are fertilizer markets coping with the continued closure of the Strait of Hormuz? Joseph Glauber and Shawn Arita (18 September 2026). ifpri.org (opens in a new tab)
- IFPRI Food Security Portal — Iran War: From Fertilizer To Food Crisis? (2026). foodsecurityportal.org (opens in a new tab)
- IFPRI — Who's afraid of high fertilizer prices? Brendan Rice and Rob Vos (21 March 2024). ifpri.org (opens in a new tab)
- UN News — Middle East war risks pushing 45 million more people into acute hunger (March 2026). news.un.org (opens in a new tab)
- AMIS — Market Monitor No. 140 (July 2026). storage.googleapis.com (opens in a new tab)
- farmdoc daily — Middle East Ceasefire Fails to Ease U.S. Fertilizer Price Pressure on Farmers, Gerald Mashange and Grant Gardner (24 April 2026). farmdocdaily.illinois.edu (opens in a new tab)
- Purdue Center for Commercial Agriculture — Middle East Conflict Revives Concerns Over Fertilizer Dependence in the U.S. and Brazil, Joana Colussi and Michael Langemeier (20 April 2026). ag.purdue.edu (opens in a new tab)
- AP (via WCAX) — Conflict in Iran sparks global fertilizer shortage, threatens food prices (27 March 2026). wcax.com (opens in a new tab)
- AgWeb — 2026 Acreage Outlook: Soybeans and Cotton Rise While Corn and Wheat Face Notable Declines (31 March 2026). agweb.com (opens in a new tab)
- The Policy Edge — OECD: Fertiliser Shocks Could Put Greater Pressure on Southern Asia's Food Supply (19 October 2026). policyedge.in (opens in a new tab)
- IFPRI — Fixing fertilizer supply chains won't be enough, experts warn (Devex) (2 October 2026). ifpri.org (opens in a new tab)
This article is for information only and is not investment, legal or trading advice. Figures are as reported by the sources cited on the date of publication.